How AI Buyer Matching Actually Works for Canadian Founder-Led Businesses Under $50M
It ranks potential acquirers by financial fit, industry, geography, and strategic value.
AI-powered buyer matching for smaller Canadian founder-led businesses scores buyers on how well they fit the business in terms of finances, industry, geography, and strategy. Instead of relying only on an advisor’s contacts, it produces a ranked shortlist that explains why each potential acquirer belongs. It makes the search broader and more accountable, while leaving negotiation, deal structure, and closing to experienced human advisors.
Why finding a buyer is the central problem for Canadian founders exiting smaller businesses
An owner can spend decades building a profitable business and still face a blank wall when asking who would buy it. Knowing customers, suppliers, and competitors is not the same as knowing qualified acquirers. The business may be sound, but its next owner remains invisible. That disconnect makes buyer discovery a separate problem from running a company well, determining its value, or preparing its records for sale.
The Canadian Federation of Independent Business reports that nearly two-thirds of small business owners plan to leave within the next decade, while only a small fraction have a formal succession plan. The federation identifies finding a qualified buyer or successor as the most cited barrier, ahead of being too busy to plan or difficulty determining business value. This is a problem of national scale. With 40% of Canadian businesses projected to change ownership in the next decade, an unresolved matching problem puts billions in business value at risk. Some otherwise viable businesses are projected to shutter rather than transfer because a suitable successor is not found in time.
How do traditional advisors find qualified buyers for a Canadian business, and where does the search break down?
When brokers lead a search, they start with people they know and buyer databases. Depending on the firm, those databases may contain a few hundred to tens of thousands of contacts, but even a substantial directory covers only part of the possible acquirer pool. An advisor then locates, qualifies, and approaches candidates through a largely manual process. That work typically takes weeks, during which confidentiality is exposed and momentum can erode. The constraint is bandwidth.
A relationship-led search naturally favors names the advisor knows. As a result, geographically distant buyers and companies in adjacent industries may never enter the conversation, even when they could see more value in the business than familiar candidates. The information behind the search can also age. Comparable transactions may be months or years old, and what an advisor remembers of a buyer’s acquisition criteria says little about whether that buyer is looking for deals now. A contact’s presence in a database does not establish current intent.
Relationships, trust, and judgment about who will actually close can distinguish a credible prospect from a merely plausible one. Why discard that judgment when the real limitation is the pool on which it operates? AI matching addresses the search constraint by expanding and updating the candidate set.
How AI buyer matching converts a relationship search into a scored, multi-dimensional process
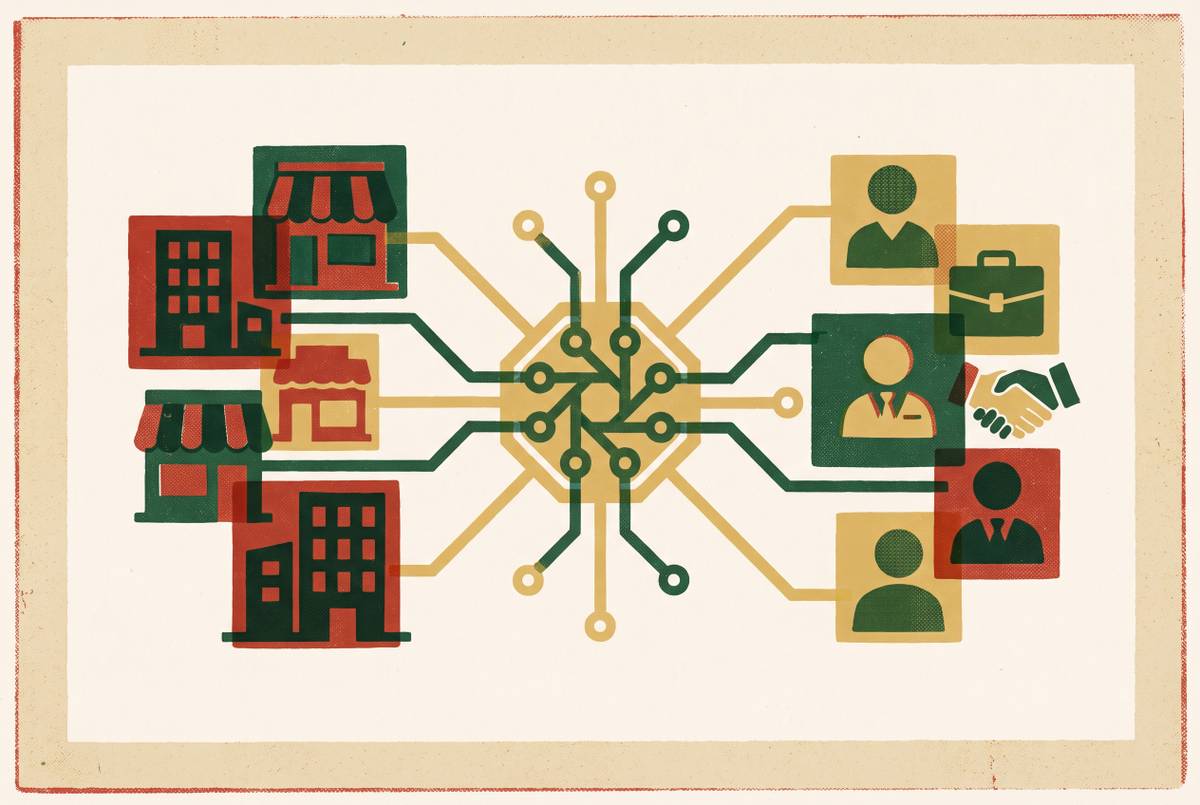
AI buyer matching works as a scoring engine. It begins with the seller’s business profile, drawing information from structured records and descriptive material. Relevant inputs include revenue, growth trajectory, customer concentration, management depth, geographic footprint, regulatory status, and technology stack. Those features become dimensions against which potential buyers are compared. The system evaluates the acquirer universe represented in its database, so its reach still depends on the information available to it.
The comparison goes well beyond industry category. Financial capacity and deal size show whether an acquisition could work, while acquisition history and integration track record help show whether the buyer has dealt with similar challenges. Strategic adjacency looks at whether this company would strengthen the buyer’s portfolio or product line. Geography adds another constraint, including a seller’s preference for Canadian ownership. Two buyers in the same sector can therefore get different scores because of what they can spend, the businesses they own, or where they want to buy.
Current behavior adds a further layer of evidence. Hiring patterns, patent filings, funding rounds, and online activity can indicate acquisition interest or a move into an adjacent market before a buyer appears through conventional channels. These are signals, not commitments to acquire. These signals help show which buyers have recently acted in ways that support a match and which have only said they want something that looks like a fit. An advisor still has to establish whether that apparent interest translates into a credible transaction.
The output is a ranked shortlist with explainable scoring. Rather than receiving hundreds of names, the advisor can see why each candidate surfaced and which dimensions support the match. As transactions move through a letter of intent, or LOI, due diligence, and close, feedback can refine future recommendations. Which buyers stay involved and which pull out shows which types of buyers go ahead with deals. The system thus links the starting profile to how deals turn out and updates acquisition criteria over time.
The buyer universe for smaller Canadian deals and what each type is actually looking for
Who sits on the other side of that shortlist? Individual buyers and first-time owner-operators often include corporate professionals who want to own a business. They tend to prioritize stable cash flow, recession-resistant sectors, and a manageable transition. Their capital is more constrained than that of institutional buyers, making financing and deal structure central to compatibility. A profitable company can still be the wrong acquisition if its price or transition demands exceed what an individual can support.
Entrepreneurship-through-acquisition searchers approach the market with a more explicit mandate. Often MBA graduates or mid-career professionals, they want to buy one business in a set industry and revenue range. Their focus can make them responsive when a business fits. It can also rule out otherwise attractive companies that sit just outside their criteria. Precise mandate matching saves both sides exploratory conversations that cannot produce a deal.
Family offices, private equity buyers, and corporate acquirers bring different motivations. Family offices may care about keeping the business and its culture intact as well as earning a financial return, while private equity buyers in smaller Canadian deals often add a business to a platform they already own. Strategic buyers can pay the highest premiums when genuine synergy exists. But that possibility depends on more than industrial similarity, because the buyer must also be in acquisition mode, have budget approval, and see a specific strategic benefit. Cross-industry acquirers are easily missed when searches begin and end with familiar sector labels.
Seller preferences make these distinctions more demanding. A strong majority of Canadian founders planning to sell consider employee protection, continuity, and legacy important, while a majority also value keeping the business Canadian-owned. Financial qualification alone cannot capture those priorities. A buyer can afford the company and still be culturally incompatible, creating disagreement even after an LOI. Buyer diversity is precisely why a single-dimension search fails, because the right acquirer for one business can be entirely wrong for another.
How valuation sets the parameters the matching system works within
Valuation defines which buyers can realistically participate in the search. A company priced at a high EBITDA multiple needs an acquirer with both access to capital and a reason to justify the premium. A smaller, owner-operated business priced on Seller’s Discretionary Earnings, or SDE, often belongs in a different buyer market.
SDE adds back owner salary and personal discretionary expenses to show the total cash flow available to one owner-operator. EBITDA matters more as businesses grow, professional managers take over the owner’s daily work, and institutional buyers use standard deal models. The earnings base changes with the operating model. Industry also affects the multiple, with recurring-revenue software, healthcare practices, professional services, distribution and light manufacturing, and food service trading within distinct ranges. A match cannot be judged from revenue alone.
Canadian founders may also encounter a gap between their expectations and the earnings buyers can price. Businesses managed for tax minimization rather than profit maximization can show compressed earnings, particularly when outside capital was never needed. Deal structure adds another consideration. Owners selling shares of a Canadian-controlled private corporation may qualify for the Lifetime Capital Gains Exemption, which can affect seller economics and compatibility with a buyer’s proposed structure. The attractive headline price and the attractive transaction are not always identical.
Recent AI adoption introduces a separate pricing uncertainty. If a company has integrated AI tools or changed its operating model, historical EBITDA may not represent its forward earnings potential. Buyers must then make assumptions about implementation speed. Even when buyers agree on the historical accounts, those assumptions can lead them to differ on whether to bid and how much to offer. Matching can identify buyers with relevant strategic interests, but it cannot make uncertain future earnings a settled fact.
What AI surfaces during matching that reveals whether a business is actually ready to sell
The same profile that identifies suitable buyers also exposes weaknesses in the business being sold. This is useful before it becomes uncomfortable. Early matching can reveal why apparently suitable acquirers would hesitate, giving the owner time to address those concerns before approaching buyers. AI makes the effect of preparation problems on the buyer pool more visible.
Owner dependence is a primary signal. If customer relationships, operating knowledge, and daily decisions reside with the founder, the buyer faces the risk that essential capabilities leave at closing. Buyers may discount that risk or decline the opportunity. Businesses with heavy owner dependence also tend to require longer transitions and more substantial earn-out structures, narrowing the group willing to bid. Management depth therefore affects both the price and the kind of successor the business can attract.
A Quality of Earnings review tests what the records demonstrate, rather than what the owner believes the company earns. Weak records, aggressive add-backs, and inconsistent reporting can make financing harder and cause deals to collapse after an LOI. Customer concentration adds a different risk. When one or two customers account for a large portion of revenue, the pool narrows toward buyers willing to accept that exposure or those already connected to those customers.
These findings become more valuable with time to act. Owner dependence, shallow management, poor records, and customer concentration can require years of deliberate preparation before sale. The practical implication is to begin matching early, even two or three years before a planned exit. At that stage, the results can guide preparation instead of presenting buyers with unresolved risks to discount. Entering the process need not mean triggering an immediate sale.
Where AI matching fits within the full M&A advisory process — and what it does not replace
Buyer discovery is one stage of a much larger transaction. AI can widen and accelerate that stage, and AI-assisted qualification is now accessible at the smaller deal sizes Canadian founders actually pursue. AI can also help with document review, financial anomaly detection, deal modeling, and scenario forecasting. After closing, AI can support synergy monitoring and longer-run performance tracking. These uses bring information together across a transaction, but people still have to carry out the deal.
A buyer’s stated intent can diverge from actual acquisition behavior, and an advisor’s experience helps distinguish enthusiasm from a credible commitment. Holding price and terms after an LOI, managing competing interests, and coordinating legal, tax, and financing advice require experienced people accountable for execution. Advisors also need to look beyond the financial profile to assess cultural fit, especially when employees, legacy, and Canadian ownership matter to the seller’s choice.
For Canadian founders in this range, the combined model pairs AI-driven discovery with institutional investment banking advisory responsible for negotiation, structure, and close. Neither role is interchangeable with the other. A ranked match is not a commitment, and it does not by itself establish confidentiality protections or replace buyer qualification. Those are distinct issues within the sale process.
The owner’s practical question is therefore not whether to choose AI or an advisor. It is whether the advisor uses AI and explains the matching process clearly enough for the owner to evaluate it. What information supports the shortlist, why did each buyer rank, and how current are the signals of acquisition interest? For an owner seeking a private sale, how will buyers be qualified and confidentiality protected during outreach? An opaque search remains a concern regardless of the technology claimed, and understanding the mechanics gives the owner a basis for asking better questions.