Family Office Acquisition Criteria for Operating Businesses
Family offices weigh cash flow and management continuity over maximum price.
Family office acquisition criteria for operating businesses reflect a different ownership model. Patient capital, legacy concerns, and principal-led decisions shape both what these buyers acquire and what they offer sellers. Knowing how those factors work together helps an owner decide whether a family office is the right buyer and get the business ready.
Why family offices have become a serious buyer class for operating businesses
Family offices have moved from passive allocation toward direct ownership and are now a major group of buyers in lower-middle-market M&A. Their direct investments now occupy a much larger share of portfolios, and the scale of their acquisition activity has grown substantially. Sellers who treat them as a secondary option risk overlooking buyers whose interests may fit the business particularly well.
Direct ownership cuts out a layer of investment fees, and offices founded by entrepreneurs often want control over businesses they understand. The move from one generation to the next also helps drive the shift toward direct investment.
How family office capital differs structurally from private equity capital
A private equity fund must return capital to its limited partners within a set time, so every acquisition thesis must include a plan for an eventual exit. A family office invests from its own balance sheet without an external investor demanding repayment on a schedule. It can therefore hold a business for decades, sometimes permanently. Family offices assess whether the business can keep producing value over a long hold.
That horizon changes both return targets and financing. Family offices generally target lower internal rates of return while seeking higher cumulative multiples over longer compounding periods. They also use far less debt, reducing debt service and leaving more free cash flow available for reinvestment. A family principal or investment committee may need to approve the acquisition, making the decision slower and more personal than a PE partnership vote.
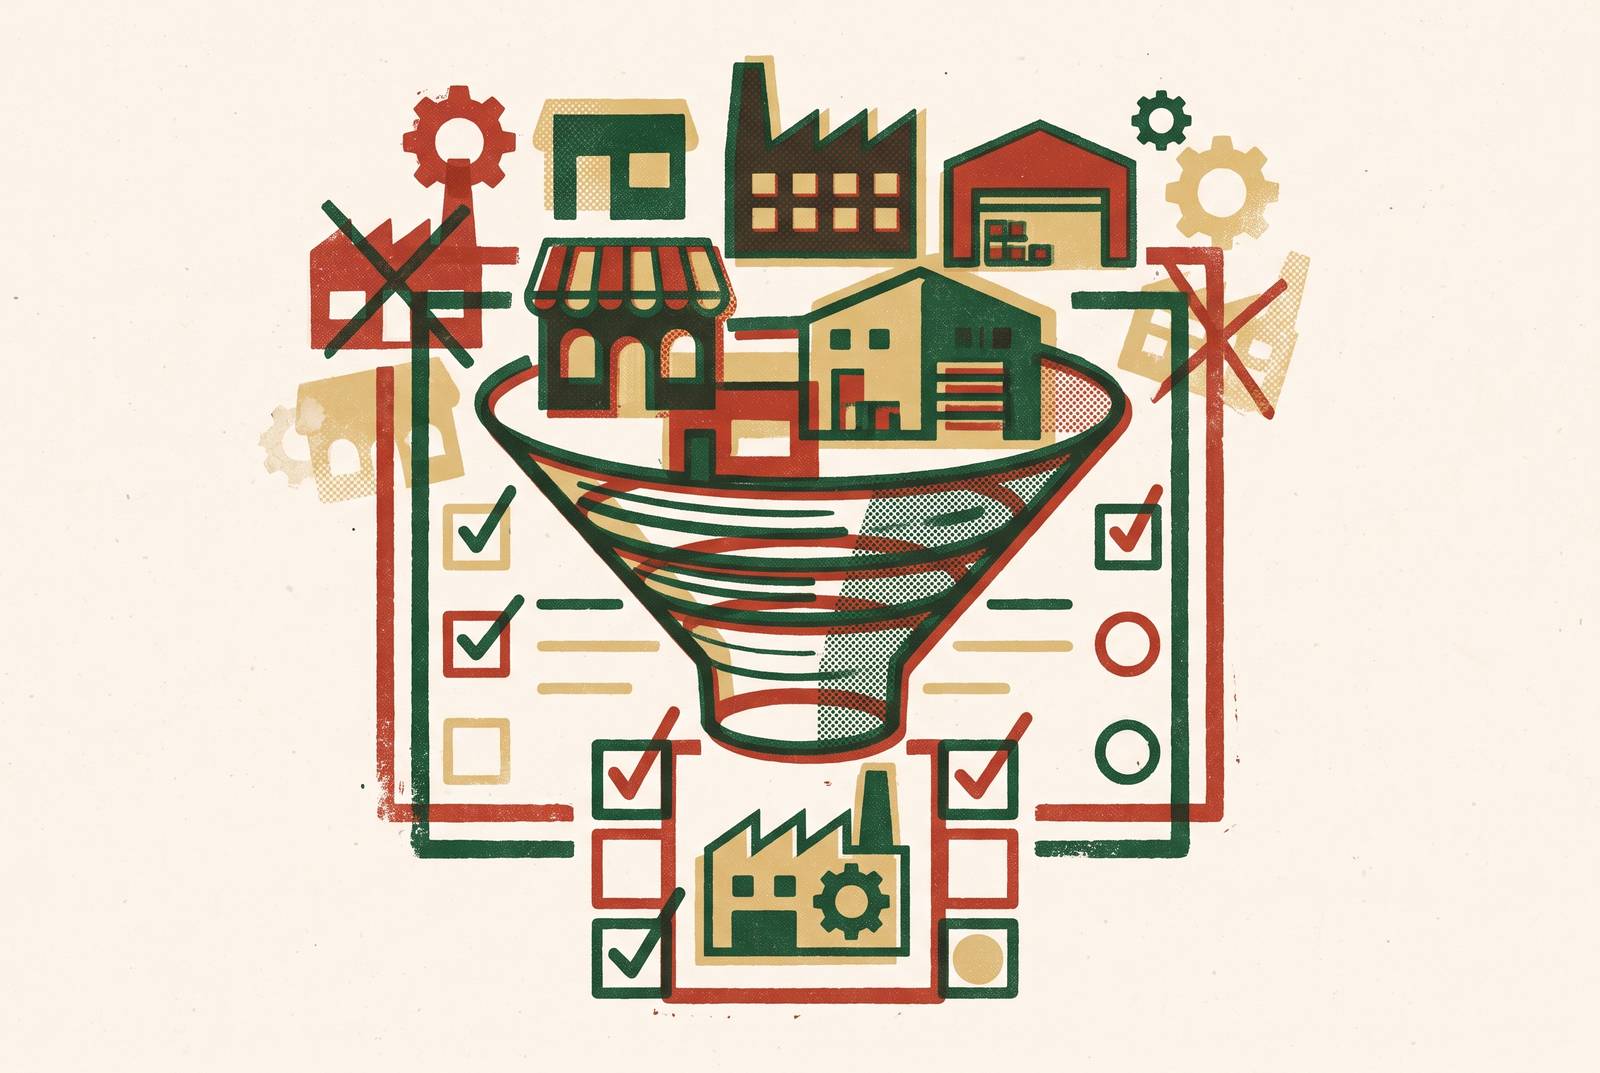
The five criteria family offices actually screen on
Cash flow quality is the foundation of the screen. Buyers look for recurring or repeat revenue, healthy gross margins, and financial statements that describe the business without extensive normalization. In Portal Drive Partners’ acquisition of a specialty distributor, limited addbacks gave lenders a cleaner story and reduced negotiation friction. The significance extends beyond accounting compliance. For a buyer expecting to own the company for a decade or more, clean financials signal operational maturity.
The business must also be the right size for the buyer’s mandate. Family offices are most active in a mid-market enterprise value band, with fewer direct-deal mandates below it and only the largest family platforms participating above it. Buyers also have set ranges for EBITDA targets, so sellers need to check which family office tier fits before spending time on outreach. The Portal Drive Partners case does not supply a numerical benchmark for either measure.
Sector alignment asks whether the family understands the business it would own. Family offices are active in consumer businesses that generate cash and have proven unit economics, industrials with an energy-transition angle, and healthcare services where demographics support demand. A family with relevant operating experience may justify a premium over a generic buyer because that expertise reduces post-close risk. The distributor case shows why the business’s position matters, especially its territorial manufacturer exclusivities, but gives no details of the family’s industry background. Sellers therefore need to check sector fit directly, since few family offices are broadly sector-agnostic.
Management continuity allows ownership to change without disrupting operations. Family offices usually rely on the management already in place instead of bringing in their own operating team, so too much reliance on the founder can cause problems with valuation and deal structure. The Portal Drive Partners distributor did not have a full management team, but the owner had a trusted deputy and a plan to add someone responsible for day-to-day operations. That distinction matters because a credible succession plan can make a management gap workable. A founder who remains the main customer contact, technical resource, and de facto COO presents a different risk from one already transferring those responsibilities.
Avoidance of financial engineering scenarios completes the screen. Family offices generally pass on turnarounds, pre-profitability businesses, hyper-growth tech-style scaling, and highly leveraged acquisitions because they want businesses that generate cash reliably and have clear room to grow. They are not seeking a sequence of venture-style funding rounds or a transformation bet. The underlying caution reflects a family balance sheet on which a bad acquisition can permanently impair multi-generational capital.
Durable market position and cultural fit as underwriting factors, not soft considerations
A long hold makes competitive durability part of underwriting. Lee and Stein say buyers look for defensible niches, long-standing ties with customers or vendors, and mission-critical products or services. Market leadership need not mean being the largest company. It means having a clear explanation for why customers choose the business and why they stay. Pricing power, concentration, and supplier dependencies matter because the buyer must live with them for a long hold, beyond the time it would take to manage them until a sale.
Cultural alignment has a similarly practical role. Whether the partners agree on how to treat customers and employees and run the business affects their ability to protect its value after closing. Surfacing those views early helps both parties decide whether diligence is worth its cost. The Portal Drive Partners seller “was not chasing the highest number” and instead wanted confidence that employees, vendor relationships, and the reputation he had built would be protected. That conversation happened early and shaped the process, showing that cultural fit was a selection criterion.
How family office deal structure differs from PE terms — and what that means for a seller's net outcome
PE typically offers a higher headline multiple for an identical business, and sellers focused on maximum upfront price will generally find it stronger on that measure. A family office offer may still look different when the seller weighs debt, deferred proceeds, and the risk they will keep. Acquisition debt is often well under half of the purchase price, giving the business more room for reinvestment and downside protection. That cushion matters particularly to a seller who stays involved or retains equity.
Rollover equity is often optional in family office transactions rather than required, and the requested share is typically lower when it is included. Earnout arrangements are generally softer, with less escrow risk, less contingency, and a longer horizon for realizing deferred proceeds. These differences do not automatically make the family office bid more valuable. Seller financing, rollover equity, and earnouts need to be modeled on a risk-adjusted basis with an advisor who can compare both scenarios. Sell-side advisors who run competitive auctions still disagree on whether that calculation makes up for the gap in headline price.
Sector expertise can further change the comparison. A family office with relevant operating knowledge and portfolio synergies may pay more than a generic buyer because it sees less post-close risk. Legacy commitments also carry value for some founders, including preserving the brand, keeping headquarters in place, and retaining employees. Those commitments are not interchangeable with cash, nor do they have a simple monetary equivalent in a PE offer. The better outcome depends on what the seller wants to preserve, receive, and remain exposed to after closing.
The deal-killers that end family office diligence after the buy box clears
Passing the acquisition screen is necessary but does not settle diligence. Customer concentration is the most common deal-killer, whether one customer accounts for an outsized revenue share or the top five collectively dominate it. Patient ownership makes that exposure consequential because the family must bear it for years. Sellers with substantial concentration may face price or earnout adjustments if they cannot reduce it before a process.
Contracts can reveal a related weakness. Key customer, vendor, or exclusivity agreements may require consent on a change of control, and an unobtainable consent can unravel an otherwise sound transaction. The Portal Drive Partners distributor illustrates the positive case because durable, transferable territorial manufacturer exclusivities were central to the investment thesis. Historical performance also needs to support management’s projections. A large gap can suggest weak forecasting or that management is showing only part of the picture, while too many addbacks can lead to disputes and re-trading.
Legal and governance uncertainty creates further obstacles. Ambiguous intellectual property ownership and significant related-party transactions benefiting insiders can make the acquisition difficult to underwrite. How readily management shares references and financial information also affects the buyer’s confidence that they can work together for a long time. Delay or resistance can become evidence of future operating friction. Most of these issues can be addressed before a sale, making diligence preparation a way to protect a promising match as well as assemble documents.
The sourcing reality: why family offices almost never find sellers through listing platforms
Even a well-prepared business may fail to reach the right buyer. Family offices find most direct deals through warm introductions and networks they already know, so sellers who rely on public listings or unsolicited outreach largely miss those opportunities. Many offices issue no press releases, publish no returns, and raise no fund. Their mandates and activity can be difficult for an owner to see. A lack of inbound interest therefore does not necessarily establish a lack of fit.
The practical response is relationship-based outreach matched to the family’s sector interests. For founders outside those networks, an advisor with existing family office relationships and a buy-box matching process offers a more relevant route than generic distribution. AI-driven buyer matching can support that task by helping connect a business with suitable acquisition criteria, but it does not replace the introduction or relationship. Process timing matters as well as access. A hard letter-of-intent exclusivity window must leave time for principal-level approval, which can take longer than a PE decision.
How to position a business for a family office buyer before entering a process
Preparation starts with reducing owner dependence. Documenting processes, developing next-level managers, and transferring key customer and vendor relationships give a buyer evidence that the company can operate without the founder’s daily presence. The goal is not to remove the founder from the business entirely. Staying after closing, as the Portal Drive Partners seller did, can be welcome when the business does not depend on that involvement for survival.
Financial preparation should happen before diligence begins. Reducing addbacks, resolving related-party transactions, clarifying intellectual property ownership, and strengthening reporting infrastructure remove sources of uncertainty before they become negotiating points. Customer concentration needs the same early attention through the development of additional customers. Where it cannot be reduced in time, an open explanation and a clear plan are better than a surprise. Lee and Stein argue that getting the finances in order early tends to improve both terms and valuation.
Identifying sector-aligned family offices and the right introductions belongs before a broad process, as does deciding how much weight to place on legacy, employee continuity, continued involvement, and upfront price. That clarity makes it easier to distinguish a suitable partner from a superficially attractive bid. The work takes time because management development, customer diversification, and trusted buyer relationships cannot be compressed into diligence. A one-to-three-year preparation period is therefore substantive rather than excessive, and a three-year runway is most useful when it begins before urgency determines the seller’s choices.